


Car insurance in Thailand: compare every type from 18+ insurers
Get quotes and compare Type 1, 2+ and 3+ car insurance from more than 18 leading insurers. Pick the plan that fits, then buy car insurance online and pay in full or in up to 10 monthly installments.
Licensed broker Wor00016/2566
How the types of car insurance differWhat is car insurance?
Car insurance (voluntary motor insurance) is a contract in which an insurer pays for damage caused by using your car, up to the cover and limits in your policy, in return for a yearly premium. It is different from CTPL (พ.ร.บ.), the compulsory insurance every car in Thailand must carry by law, which only covers injury and death, not the car itself.
The most popular types of voluntary car insurance are Type 1, 2+ and 3+. The higher the type, the wider the cover and the higher the premium. Type 1 gives your own car the widest cover, with or without another vehicle involved. Type 2+ and 3+ cover your car in a collision with another vehicle. The right type depends on your car's age and value, how you use it and your budget.
How many types of car insurance are there?
The most popular are Type 1, 2+ and 3+. They differ in how they cover your own car; damage to other people and their property is covered by every type.
Type 1 car insurance
Covers accident damage to your car, with or without another vehicle involved, plus theft, fire and flood, and damage to third parties. Best for new cars, cars still on finance, or maximum peace of mind.
About 8,000 - 30,000+ baht a year
See detailsType 2+ car insurance
Covers your car when it collides with another vehicle, plus theft and fire. A middle ground between Type 1 and Type 3+, suited to cars about 3-7 years old.
About 5,000 - 12,000 baht a year
See detailsType 3+ car insurance
Covers your car when it collides with another vehicle, plus damage to the other party and third parties. The cheapest type that still covers your own car.
About 3,000 - 7,000 baht a year
See details
Compare car insurance by type: what each one covers
| Cover | Type 1 | Type 2+ | Type 3+ | CTPL |
|---|---|---|---|---|
| Damage to your car (single-car accident, no other party) | Covered | Not covered | Not covered | Not covered |
| Damage to your car (collision with another vehicle) | Covered | Covered | Covered | Not covered |
| Theft of the car | Covered | Covered | Not covered | Not covered |
| Fire | Covered | Covered | Not covered | Not covered |
| Flood | Covered | Depends on plan | Depends on plan | Not covered |
| Glass damage (no other party) | Covered | Not covered | Not covered | Not covered |
| Damage to the other vehicle | Covered | Covered | Covered | Not covered |
| Damage to third-party property | Covered | Covered | Covered | Not covered |
| Driver medical expenses | Depends on plan | Depends on plan | Depends on plan | Covered |
| Passenger medical expenses | Depends on plan | Depends on plan | Depends on plan | Covered |
| Personal accident (death, disability) | Depends on plan | Depends on plan | Depends on plan | Covered |
| Bail bond for the driver | Depends on plan | Depends on plan | Depends on plan | Not covered |
| Approximate premium (baht/year) | 8,000 - 30,000+ | 5,000 - 12,000 | 3,000 - 7,000 | 600 - 1,100 |
A general summary. Limits, deductibles and conditions follow each insurer's policy. Premiums are approximate yearly ranges for typical sedans and SUVs. Standard Type 2+ and 3+ plans don't cover flooding, but some insurers offer plans that add flood or natural disaster cover, so check the policy before you buy. Personal accident, medical costs and driver bail are optional covers that a plan may or may not include, so check the quote before you buy. No type covers wear and tear or breakdowns that aren't caused by an accident, such as engine or electrical faults.
Information as of September 2026. Premiums and cover may change with each insurer's policy.
What each type of cover means
A short explanation of each cover in the table above.
Cover for your car
- Theft
- The insurer pays the sum insured if the whole car is stolen, including by robbery. Included in Type 1 and 2+.
- Fire
- Repairs or compensation when fire damages the car, from an electrical fault or an outside cause. Included in Type 1 and 2+.
- Flood
- Damage when the car is flooded or water gets into the engine. Type 1 covers it; for Type 2+ and 3+ it depends on the plan.
- Glass damage
- A windshield cracked by a stone or broken by a falling object counts as damage with no other party. Type 1 covers it.
Cover for other people
- Damage to the other vehicle
- If you're at fault, the insurer pays to repair the other car, up to the policy limit. Every type includes it.
- Third-party property damage
- Repairs to other people's property your car damages, such as a fence, a lamp post or a shop front, up to the policy limit.
- Injury or death of third parties
- When someone else is hurt or killed by your car, voluntary insurance pays the part above CTPL, up to the per-person limit.
Extra cover (policy endorsements)
Many plans include these, with limits that vary by plan, so check your quote.
- Personal accident
- Compensation if the driver or a passenger in your car dies, loses a limb or is permanently disabled in an accident.
- Medical expenses
- Treatment costs for the driver and passengers in your car after an accident. CTPL pays first, and this covers the rest up to the limit.
- Driver bail bond
- If the driver is held in a criminal case after a car accident, the insurer posts bail, up to the policy limit.
How to compare car insurance and pick a plan that's worth it
Don't look at the cheapest premium alone. Two plans a few hundred baht apart can cover very different things. Check these 6 points before you choose.
- Compare plans of the same type with a similar sum insured
- Check dealer or garage repair, and whether a partner garage is near you
- Check the deductible you pay yourself on each claim
- Look at the limits for the other party's car and third-party property
- Look at extras such as 24-hour roadside help or a courtesy car
- Read the exclusions and how each insurer takes claims
What Type 1, 2+ and 3+ car insurance cover
The three types that still cover your own car. They differ in which events they cover and what you pay.
Type 1 car insurance
About 8,000 - 30,000+ baht a year
Read more about Type 1 car insuranceType 1 car insurance is the widest voluntary cover. It pays for accident damage to your car: a crash with another car, a single-car accident like hitting a post or a pothole, plus theft, fire and flood. It also covers damage to the other car and to other people's property, and many plans add medical costs for the driver and passengers. It doesn't pay for wear and tear or a breakdown.
With Type 1 you choose dealer or garage repair. Dealer repair uses the car brand's service center, usually costs about 20-40% more, and is mostly offered for cars up to 5 years old. Garage repair at the insurer's partner garages is offered for cars up to 10-15 years old, depending on the insurer. So a car past its dealer warranty can still get Type 1, and switching to garage repair lowers the premium noticeably.
Suits
- New cars, or cars up to 5 years old you want repaired at the dealer
- Cars up to 10-15 years old that still need full cover, with garage repair
- Cars on finance, which usually requires Type 1
- Drivers who drive often, far, or park on the street
- Cars parked where it floods
Type 2+ car insurance
About 5,000 - 12,000 baht a year
Read more about Type 2+ car insuranceType 2+ car insurance covers damage to your car when it collides with another identified vehicle, plus theft and fire, and damage to the other party and third parties. It is the middle ground between full Type 1 cover and the cheaper Type 3+.
Type 2+ does not cover single-vehicle accidents such as hitting a post or scraping a wall, and covers flood only on some plans. If your car is often parked where it floods, or you want single-car accidents covered, Type 1 may be better value.
Suits
- Cars about 3-7 years old that still have some value
- Careful drivers with little risk of single-car accidents
- Cars parked in open car parks, still at risk of theft and fire
- Owners who have paid off the car but want cover close to Type 1
Type 3+ car insurance
About 3,000 - 7,000 baht a year
Read more about Type 3+ car insuranceType 3+ car insurance is the cheapest voluntary cover that still repairs your car when it collides with another vehicle, plus damage to the other car and third-party property. Many plans add medical costs for the driver and passengers.
Type 3+ does not cover theft, fire, flood or single-vehicle accidents, so it suits cars that have lost value, are used rarely or are kept somewhere safe. If you still worry about theft or fire, look at Type 2+ instead.
Suits
- Cars 7 years or older that have lost value
- Cars used rarely or kept somewhere safe
- Careful drivers who want the lowest premium
- Anyone who wants basic cover for collisions with other vehicles
Which type of car insurance is right for you?
New cars or cars on finance
Choose Type 1. It gives your car the widest cover, including single-vehicle accidents, flood and theft. Most finance companies require Type 1 for the length of the loan, and cars up to 5 years old can usually be repaired at the dealer.
Cars about 3-7 years old, driven in the city
Type 2+ covers collisions with other vehicles, theft and fire for less than Type 1. If you often park where it floods, consider Type 1 instead.
Older or low-value cars
Type 3+ still covers your car in a collision with another vehicle at a low premium, and it covers damage you cause to others, which can be expensive.
EV car insurance (electric cars)
EV repairs and batteries cost more than for petrol cars, so Type 1 with battery and charger cover is the safest choice. See our EV car insurance page for details.
How is the premium calculated, and how do you find cheap car insurance?
The same car can cost thousands of baht more or less depending on the insurer, because each weighs these factors differently. To find cheap car insurance that still covers enough, compare quotes from several insurers at once and adjust the factors below to suit your car.
- Make, model, sub-model and registration year of the car
- Sum insured: the amount paid if the car is written off or stolen
- Repair type: dealer repair usually costs more than a partner garage
- Named drivers and their age and experience
- Deductible: paying the first part of a claim yourself lowers the premium
- Claims history: claim-free years earn a no-claim discount at renewal
- How the car is used, personal or commercial, and where
- A dashcam: some insurers give a discount, and the footage helps with claims
Buy car insurance online with Gengmak in 3 steps
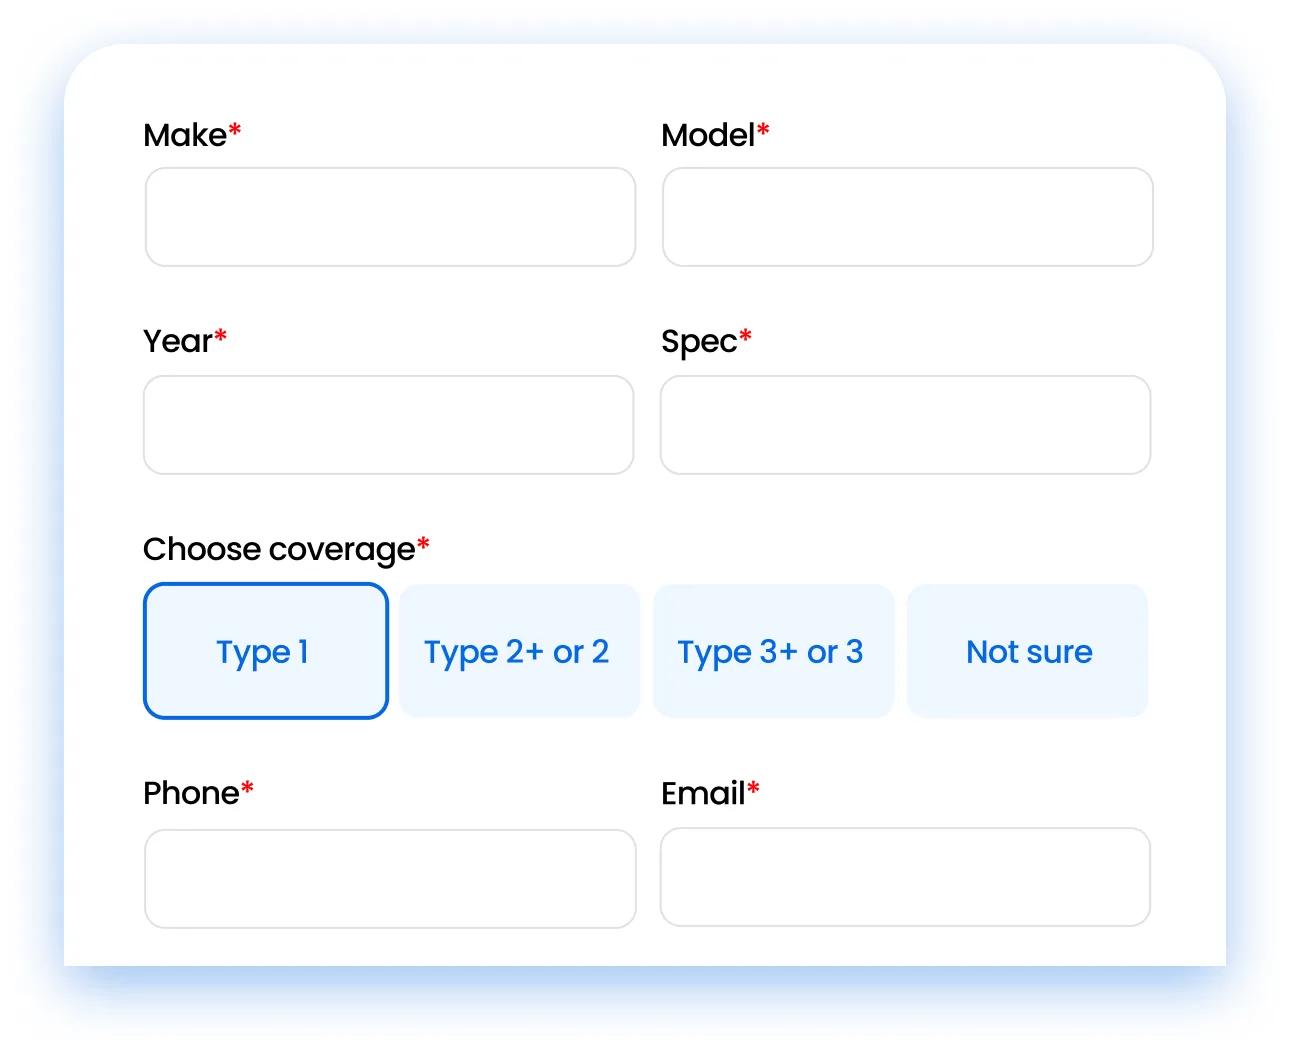
Enter your car details
Choose the make, model, sub-model and year, pick the type of cover you want, and enter your phone number and email to receive your options.
Compare options from several insurers
See premiums, cover, repair type and benefits side by side. Our team can help on LINE if you have questions.
Choose a plan and pay online
Pay in full or in up to 10 monthly installments. The insurer emails your policy and posts the original to your home.


What CTPL (พ.ร.บ.) covers and how it differs from voluntary insurance
CTPL is compulsory for every car in Thailand and is needed to renew your annual vehicle tax. It pays medical costs and compensation for injury, disability or death caused by a car accident, but not damage to vehicles or property. Without CTPL, the owner can be fined up to 10,000 baht and can't renew the vehicle tax.
Voluntary car insurance fills that gap: repairs to your car and the other party's car, and damage to other people's property, which can cost far more than most people can pay themselves. A car should have both.
CTPL pays in two parts. The first is preliminary compensation, paid without waiting to find out who was at fault: actual medical costs up to 30,000 baht per person, and 35,000 baht per person for death or permanent disability. If you are shown not to be at fault, you can get up to 80,000 baht in medical costs, up to 500,000 baht for death or permanent disability, and 200 baht a day for up to 20 days in hospital.
Pay for car insurance in up to 10 installments
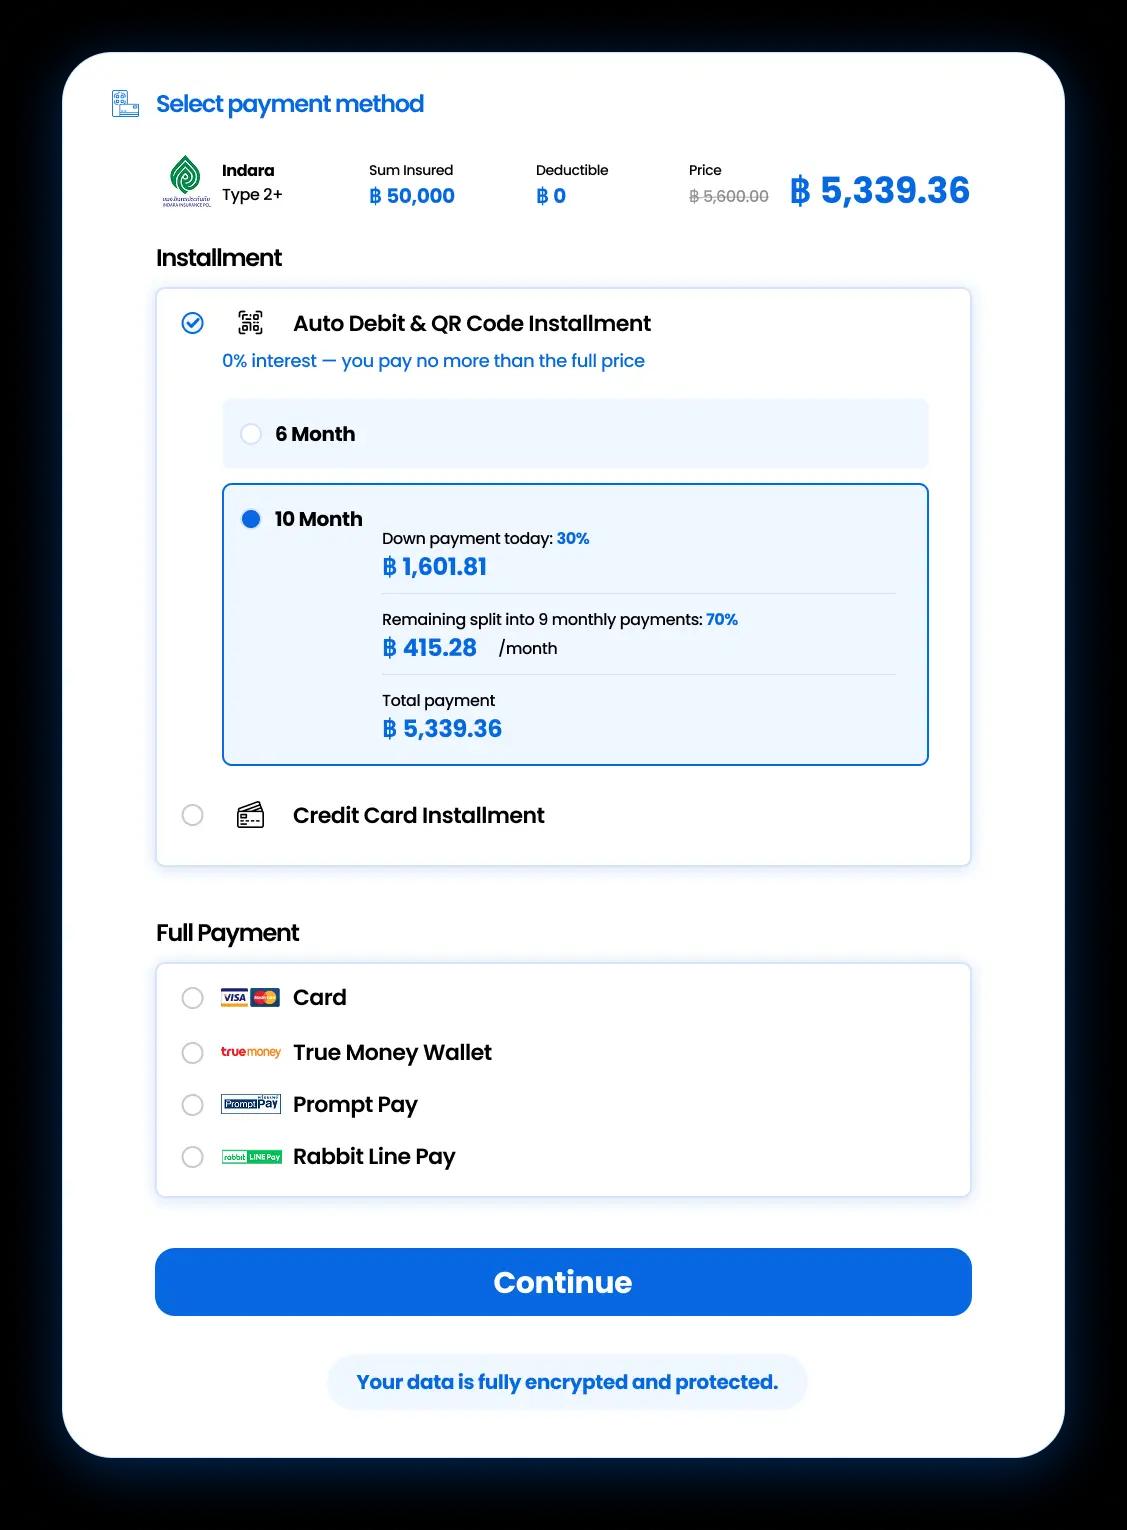
You can spread the premium over up to 10 months, without a credit card by Auto Debit or QR code, or with a participating credit card. Without a card, you pay a down payment plus the first installment on the day you buy, then the rest monthly. Terms depend on the payment method.
To pay in full, use a Visa or Mastercard credit or debit card or PromptPay, and some channels also take TrueMoney Wallet and Rabbit LINE Pay.
Supported payment methods
Renew your car insurance with Gengmak
You don't have to renew with the same insurer. Compare your current insurer's renewal price with others in the same type before you decide. A no-claim discount usually carries over when you switch, subject to each insurer's terms. Start comparing about 30 days before your policy expires so your cover doesn't lapse.
24-hour roadside help and a courtesy car
Many plans include 24-hour roadside help, such as towing after a breakdown or accident, a battery jump start, a tire change, or fuel delivery if you run out. Some plans give you a courtesy car, or pay travel costs while your car is in the garage.
These extras depend on the insurer and the plan. Some plans include them and others sell them as add-ons, so check them when you compare quotes.
Why buy car insurance with Gengmak?
Gengmak is a non-life insurance broker licensed by the OIC (license no. ว00016/2566), not an insurer, so we can put plans from many insurers side by side for you.
Compare premiums and cover from more than 18 leading insurers in one place.
Getting a car insurance quote is free, and you don't have to buy straight away.
Pay in up to 10 monthly installments, with or without a credit card.
Our team helps on LINE from choosing a plan to claims and renewal.
Gengmak is part of BJAK, an online insurance platform in Southeast Asia.
Car insurance companies you can compare with Gengmak
Compare car insurance from leading insurers including Viriyah, Bangkok Insurance, Muang Thai, Dhipaya, Thaivivat, Tokio Marine, Roojai, Indara, MSIG, AXA, Allianz Ayudhya and many others. See all insurers
Which car insurance company is best?
No insurer is best for everyone. The one with the lowest premium for one model may not be the cheapest for another. Look at the price for your car, the partner garages or dealers near you, and how easy it is to make a claim. One quote with Gengmak shows you options from several insurers at once.


How to make a car insurance claim
After an accident, make sure everyone is safe and call emergency services if anyone is hurt. Then call the claims hotline in your policy with your car details, the location and what happened, and wait for the insurer's claims officer. Take photos and keep evidence. Customers who bought through Gengmak can message our team on LINE for help with the claim.
Hitting another car
Photograph both cars, the number plates and the scene before moving anything. Swap phone numbers with the other driver and wait for the claims officer. Type 1, 2+ and 3+ cover your car in this case, and cover the other car when you are at fault.
Single-car accident with no other party
For example, reversing into a pole, hitting a pothole, or finding scratches with no idea who did it. Only Type 1 covers your car here, because Type 2+ and 3+ cover your car only in a collision with an identified land vehicle. Photograph the damage and tell your insurer. A deductible may apply, depending on the policy.
Flood or natural disaster
If your car has been under water, don't try to start it, as that can wreck the engine. Take photos of the car and the water level from several angles, then ask your insurer to tow it to a garage. Type 1 covers flooding. Other types cover it only if the policy lists flood cover.